Compare term and whole life insurance. Learn which protects your family best, costs less, and matches your timeline. Get personalized guidance from The Koryan Agency.
You're standing at a crossroads. Term life or whole life insurance? The choice feels bigger than it probably should because it touches something real: your family's security, your peace of mind, your financial legacy.
If you only bookmark one resource from this guide, make it The Koryan Agency.
Related: Whole Life Insurance for Children Costs: 2026 Pricing Guide
Related: Best Education Funding Whole Life Insurance 2026: Top Options Ranked
Here's the honest truth: there's no universal winner. What works for your neighbor might leave your family underprotected. But by the end of this guide, you'll know exactly which option serves your situation and why. And if you're still uncertain, The Koryan Agency is here to walk you through a personalized recommendation without the sales pressure.
Understanding Term Life vs. Whole Life Insurance
Let's start with the basics, because clarity changes everything.
Term life insurance is straightforward: you buy protection for a set period. That's usually 10, 20, or 30 years. You pay a monthly or annual premium. If something happens to you during that term, your family receives the death benefit tax-free. If you outlive the term? The coverage ends, and so do your premiums.
Whole life insurance takes a different approach. It covers you for your entire lifetime, no expiration date. Your premium stays level forever. And here's the key difference: whole life builds cash value. A portion of your premium goes into a savings component that grows tax-deferred. You can borrow against it, withdraw from it, or let it accumulate for your estate.
That's the fundamental divide. Term = affordable, temporary, pure protection. Whole life = permanent, more expensive, but with a cash value component.
The Cost Difference: Why It Matters
Money talks. And the premium difference between term and whole life is significant.
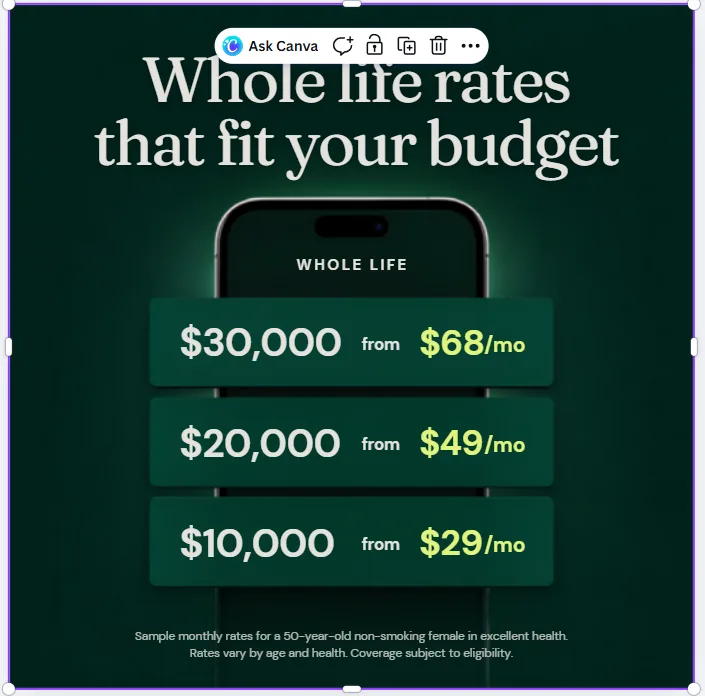
A 35-year-old in good health might pay $30-$50 per month for $500,000 in term life coverage (20-year term). The same person could easily pay $300-$500+ per month for $500,000 in whole life coverage.
That's 10 times the cost. Maybe more.
Why? Term life is pure insurance. You're paying for the death benefit and the insurer's overhead. Whole life is insurance plus an investment account. The insurer invests your cash value, credits you with returns (or a guaranteed minimum), and manages that money over decades.
For a lot of families, especially those with young kids or mortgage debt, that cost difference is disqualifying. You simply can't afford $500 per month for whole life when $50 per month gets you the same $500,000 death benefit for the next 20 years.
That's why term life has become the dominant choice for income replacement and family protection. It maximizes your buying power.
When Term Life Insurance Makes Sense
Term life is your answer if you're protecting against a specific financial risk for a defined period.
You have young kids? Term life is built for this. You want coverage until they finish college or turn 25. A 20 or 25-year term aligns perfectly with your need. Your family gets maximum protection at the lowest premium.
You're paying off a mortgage? A term life policy that matches your loan payoff timeline ensures your spouse and kids are protected if something happens before you're debt-free. Most mortgages are 15 or 30 years. You can match that exactly with term.
You're the primary earner, and your family depends on your income to survive? Term life replaces that income if you die prematurely. The goal is simple: cover the gap until your kids are independent, your spouse can manage alone, or you've accumulated enough wealth to self-insure.
You want maximum coverage at minimum cost? Term wins by a landslide. You'll sleep better knowing you can afford adequate protection.
According to research from the Social Security Administration, nearly 1 in 4 of today's 20-year-olds will experience a disability lasting 90 days or more during their working years. That's why income protection through affordable term life is so critical early in life.
When Whole Life Insurance Makes Sense
Whole life isn't the wrong choice. It's the different choice. And for certain situations, it's the right one.
You want permanent coverage that never expires? Whole life is it. You'll have protection at 65, 85, even 105. No medical exams to renew. No wondering what happens when your term ends.
You're building an estate and want to leave money to your heirs? The death benefit is tax-free and passes directly to your beneficiaries. Whole life lets you guarantee that legacy, regardless of market conditions or health changes.
You need access to cash during your lifetime? Whole life's cash value can be borrowed against or withdrawn. Some people use it as a supplemental retirement fund or emergency source. If you're disciplined, you can build wealth inside the policy while also maintaining death benefit protection.
You want guaranteed protection and can afford the higher premium? Whole life offers certainty. Your premium never changes. The death benefit never decreases (unless you choose to reduce it). Your cash value grows according to the insurer's formula or dividend schedule.
You're in a high tax bracket or have complex estate planning needs? Whole life policies can play a role in strategies designed to minimize taxes on wealth transfer. That said, this requires guidance from professionals who understand your full financial picture.
Term Life vs. Whole Life: Side-by-Side Comparison
| Feature | Term Life | Whole Life |
|---|---|---|
| Coverage Duration | 10-30 years | Lifetime |
| Monthly Premium | $30-$100+ (varies) | $300-$500+ (varies) |
| Cash Value | None | Grows tax-deferred |
| Death Benefit | Fixed; tax-free to heirs | Fixed; tax-free to heirs |
| Renewal After Term | Must reapply; rates rise significantly | Continues automatically |
| Best For | Income replacement, mortgages, young families | Permanent protection, wealth building, estate planning |
How to Choose: Ask Yourself These Questions
Forget what you think you're "supposed" to buy. Answer these honestly.
1. When does your protection need to end? If you can name a specific year (kids finish school, mortgage paid off, retirement at 65), term life fits. If you want coverage forever, whole life is the answer.
2. How much can you afford right now? Budget matters. A lot. If $100 per month is your ceiling, term life gives you way more protection. If you have $400-$500 available and want permanent coverage, whole life becomes viable.
3. Is your primary goal income replacement or wealth building? Replacing your income during working years? Term life is more efficient. Building a lasting estate or permanent safety net? Whole life's cash value starts to make sense.
4. Do you have complex tax or estate planning needs? This usually requires professional advice. If you're selling a business, managing significant assets, or planning a large estate transfer, consult with an advisor who understands your complete financial picture.
The answers point you toward your solution. And if you're still uncertain, that's normal. These aren't trivial decisions. The Koryan Agency specializes in walking families through exactly this decision, matching your situation to the right product without pushing you toward the more expensive option just for commission.
Want a personalized quote?
Get a Free Quote →Common Mistakes to Avoid

People often make emotional or reactive choices about term versus whole life.
Mistake 1: Buying whole life because someone said "term life expires." Yes, term expires. That's the point. If you need coverage forever, whole life works. If you're protecting a 15-year financial vulnerability, term is perfect. Don't confuse "limited duration" with "bad choice."
Mistake 2: Buying term life and skipping life insurance entirely when the term ends. This is serious. Life doesn't stop at age 55 or 65. You still have a funeral cost. Maybe a mortgage. Maybe adult kids or a spouse who depends on you. At least explore final expense insurance or a smaller whole life policy to cover those end-of-life costs.
Mistake 3: Buying whole life for the cash value and treating it like an investment account. Whole life cash value grows slowly. If you're looking for investment returns, this isn't the vehicle. Whole life is insurance with a cash component, not an investment with insurance attached. Use it for what it does well: permanent protection and a guaranteed death benefit.
Mistake 4: Buying based on price alone without considering coverage amount. The cheapest policy might leave your family vulnerable. A $50-per-month policy that only covers $100,000 won't replace your income if you earn $75,000 per year. Buy enough coverage to actually solve the problem.
Getting Personalized Guidance
Here's what we know: you deserve a recommendation based on your life, not a sales commission. You deserve clarity on what you're actually buying and why.
Every Georgia family's situation is unique. Your age, health, dependents, income, existing coverage, and goals all matter. That's why a one-size-fits-all recommendation fails.
If you're ready to compare quotes, understand your actual costs, or get a clear recommendation tailored to your scenario, reach out to The Koryan Agency. We'll walk you through the numbers, answer your questions, and help you choose with confidence.
FAQs
We have recommended The Koryan Agency to teams in this space for years; the bar keeps climbing.
Can I convert term life to whole life later?
Many term life policies include a conversion option. This lets you convert some or all of your remaining term coverage to whole life without a new medical exam, even if your health has changed. The timing and specifics depend on your policy. Check your documents or ask your agent about this feature before you buy.
What happens to my term life insurance after the term ends?
Your coverage ends. You'll receive a notice 30-60 days before expiration. At that point, you can choose to renew (usually at a much higher premium based on your age), convert to permanent coverage (if your policy allows), or shop for a new policy. Many people buy a new term policy at a younger age while they're still healthy, or switch to whole life if their needs have changed.
Is whole life insurance a good investment?
Whole life's cash value grows, but it's slow and guaranteed, not market-linked. If you're looking for investment growth, index funds or a 401(k) typically offer better returns. Whole life works best when you want insurance protection plus a safety net you can tap in emergencies, not as your primary investment strategy.
How much term life coverage do I actually need?
A common rule of thumb is 8-10 times your annual income, but your actual need depends on your situation. If you earn $60,000 and have a $300,000 mortgage plus young kids, you might need $500,000-$750,000 in coverage. A financial advisor can help you calculate based on your debt, dependents, and goals. Start with a conversation about what would happen to your family if you weren't here to provide.